TripBuddy Guide
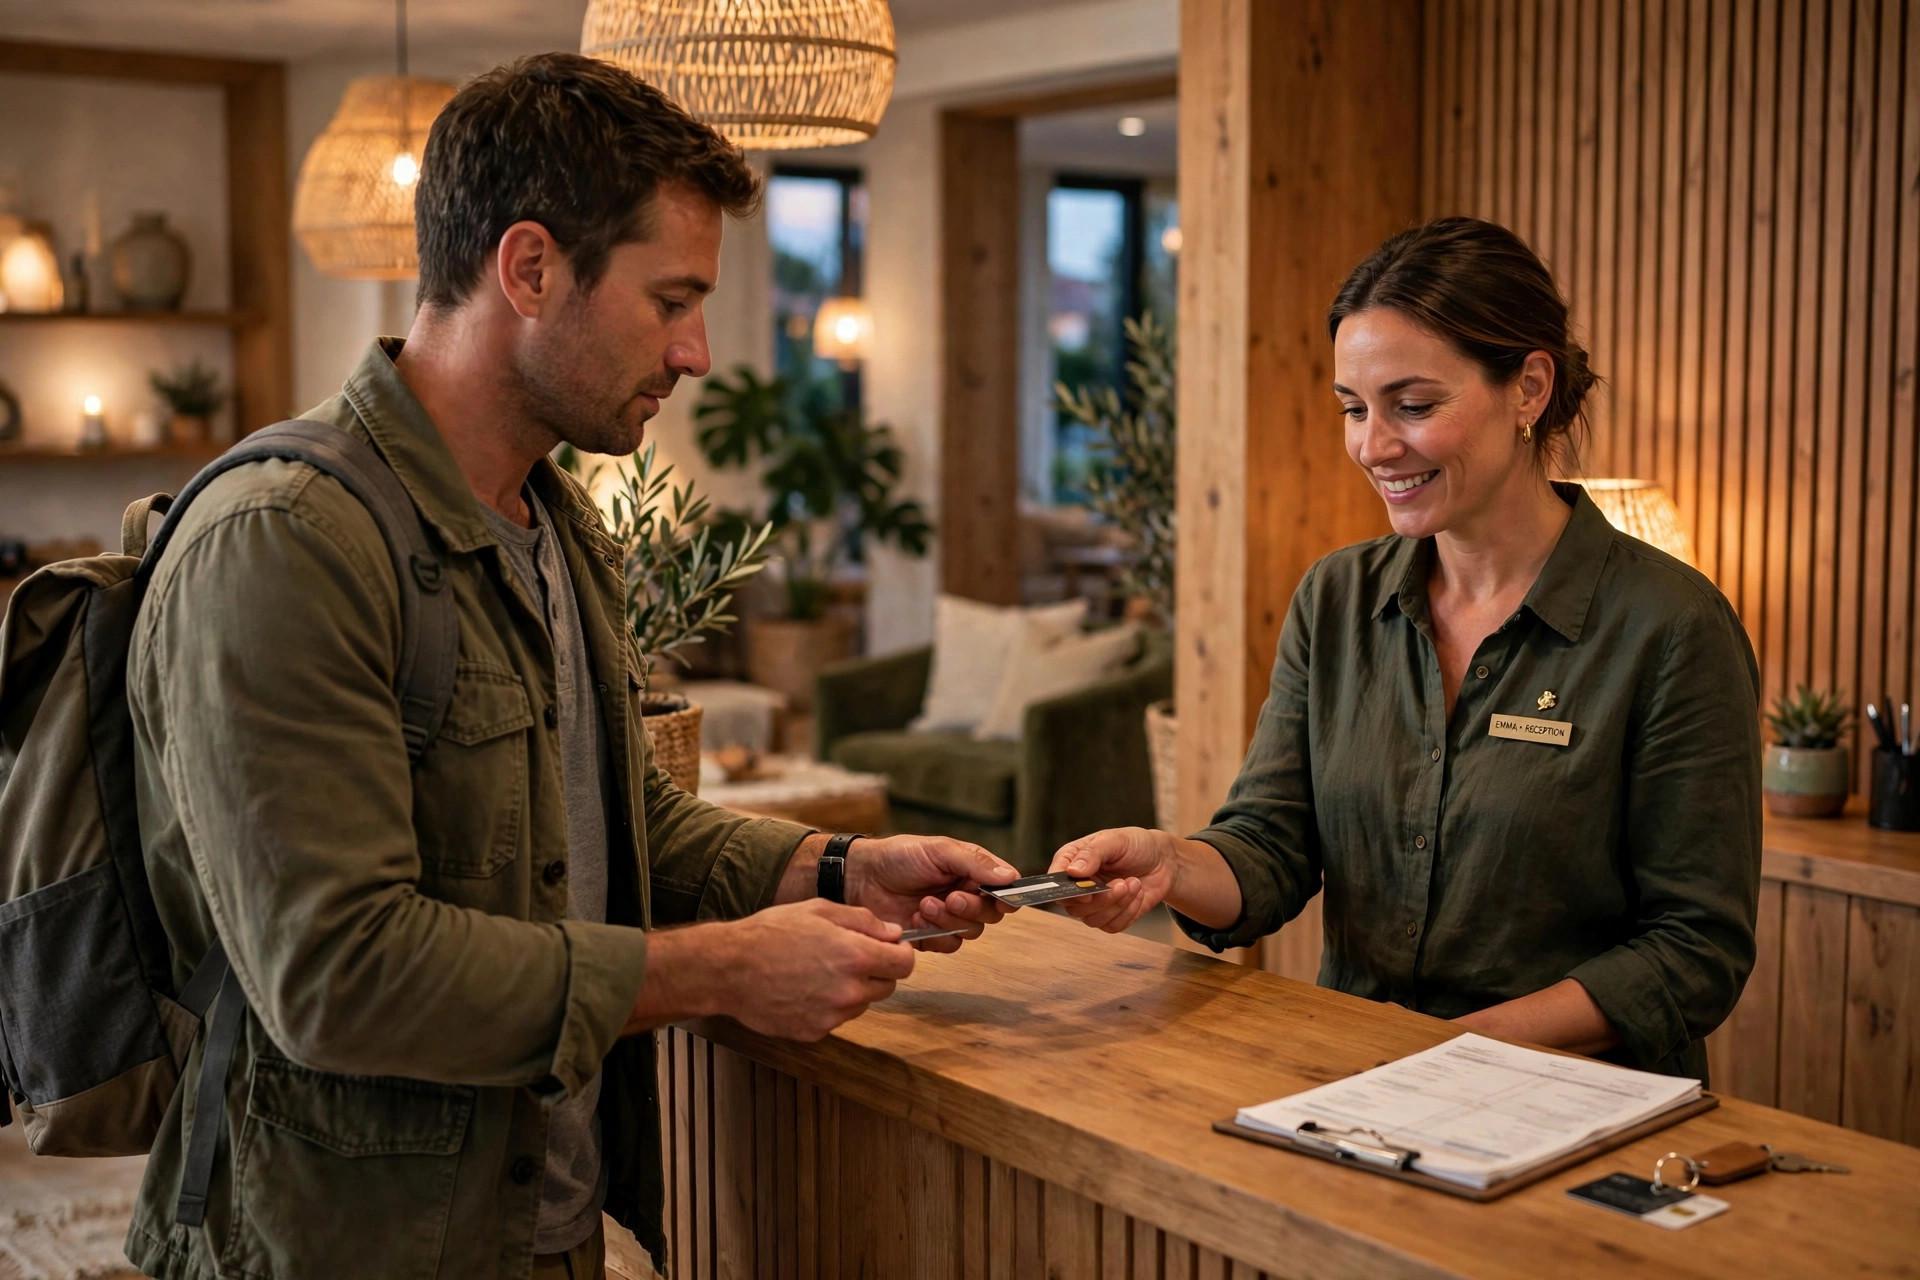
You’ve paid for your room — or reserved it with a card — and at check-in the front desk asks for that card again. A day later, a pending charge appears that isn’t your room rate. A week after checkout, it’s still there. Welcome to the hotel card hold: the most common, least explained transaction in travel.
Nothing shady is usually happening. But holds cause real problems — declined cards, drained debit balances, vacation budgets quietly frozen — when travelers don’t know they’re coming. Here’s how they actually work and how to stay ahead of them.
Sign up for monthly travel guides
The short answer
- A hold (pre-authorization) is a temporary reserve on your card for the room, taxes, and possible extras — not a final charge, but it does reduce your available credit or balance while it lasts.
- Holds typically cover the stay plus an incidentals amount set by the hotel’s policy.
- On credit cards, holds usually fall off within a few days of checkout. On debit cards, the same hold can lock up real cash for much longer — the single biggest gotcha in this whole topic.
- You can ask at check-in exactly how much will be held and what it covers. Good hotels answer without blinking.
Why hotels place holds at all
From the hotel’s side, the logic is simple. They are handing you a room full of chargeable things — minibar items, room service, movies, the phone, potential damage — and they want assurance they can bill for them without chasing you afterward. The hold is that assurance: a guarantee that funds exist, reserved in advance, settled (or released) after checkout.
Hotels also use the initial authorization to confirm the card is genuine and active, which is why a hold sometimes appears even on a fully prepaid stay: the room is paid, but the incidentals guarantee is not.
Hold vs. deposit vs. charge: three different things
- Authorization hold: a temporary reservation of funds. No money leaves your account; your available credit (or debit balance) drops until it releases.
- Security/incidentals deposit: sometimes an actual amount collected up front — more common at vacation rentals, boutique properties, and internationally — and refunded after checkout minus any charges.
- Charge: the final settled transaction. At checkout, the hotel typically settles the real total and the unused hold releases.
Listings and policies blur these words constantly. The practical question is always the same: how much of my money is unavailable, and for how long?
How much will be held?
There is no industry standard, and anyone who quotes you a universal figure is guessing. Policies vary by property and can be structured as a flat per-stay amount, a per-night amount, or a percentage on top of the room and tax. Luxury properties and resorts tend to hold more, reflecting pricier incidentals; limited-service hotels often hold less or, on prepaid rates, just a modest incidentals amount.
What you can do — and should, on any stay where it matters:
- Check the booking confirmation and the property’s policies page for “incidentals,” “deposit,” or “pre-authorization” language before you arrive.
- Ask at check-in, in plain words: “How much will you authorize on my card, and when does it release?” Write down the answer if the trip budget is tight.
- Remember it stacks with the room. On a pay-at-property rate, the hold can cover the full stay plus incidentals — a much bigger number than travelers expect.
This is the same read-the-total discipline as our resort fees guide: the surprises in hotel pricing are rarely hidden, just rarely read.
The debit card trap (read this part twice)
Using a debit card for a hotel hold is where people genuinely get hurt:
- It’s real money. A credit hold reduces available credit; a debit hold reduces the cash in your checking account. Rent, bills, and other trips keep happening while it’s frozen.
- Releases run slower. Banks can take considerably longer to restore debit funds after the hotel releases the hold than card networks take with credit. Days stretching past a week is not unusual.
- Stacks are brutal. A multi-stop trip on a debit card can mean two or three overlapping holds at once — each from a hotel you’ve already checked out of.
Some hotels also restrict debit cards at check-in entirely, or require a larger cash deposit instead. If a debit card is your only option: ask for the exact hold amount before you travel, keep a buffer in the account well above it, and get the release confirmed at the front desk at checkout. Better still is the pattern in our book direct vs. third-party guide: settle the payment method questions with the property before arrival day, not at the desk with a line behind you.
When the hold doesn’t release on time
Holds release in two steps, and delays can come from either side:
- The hotel finalizes or voids the authorization — usually at checkout. If a hold lingers, call the hotel first and ask them to confirm they’ve released/finalized it; ask for the release in writing if it’s a large amount.
- Your bank posts the release — on its own schedule, which you generally cannot speed up, though a bank call with the hotel’s confirmation sometimes helps.
Keep your folio (the itemized bill) from checkout. If a final charge looks wrong — an incidental you never used — dispute that specific charge with the folio in hand; that’s a billing error, which is different from a slow hold, and hotels fix them routinely when shown the paperwork.
Sign up for monthly travel guides
Five habits that make holds a non-issue
- Check in with a credit card, not debit, even if you prepaid with debit — the hold can ride on a different card than the payment at most properties. Ask if you’re unsure.
- Keep headroom. Don’t travel with a card within a few hundred dollars of its limit; one resort hold can decline your dinner.
- Ask the two questions (how much, when does it release) at every check-in where the budget matters. It takes ten seconds.
- Photograph your folio at checkout. It’s your evidence for every later billing question.
- Decline incidentals deliberately on tight-budget stays. Some properties will take a smaller hold or none if you opt out of charging privileges to the room. It never hurts to ask.
The decision in one paragraph
Card holds are normal, explainable, and manageable — with a credit card, a bit of headroom, and two questions at check-in, they’re a non-event. They only bite travelers who use debit cards without a buffer or never learn the amount being held. Know your hotel’s policy before arrival day, and the pending charge on your statement becomes exactly what it should be: expected.
TripBuddy may earn a commission when you book through links on this page, at no extra cost to you.
Booking a stay where the deposit policy is murky? See how TripBuddy’s hotel guidance works — we help you read the fine print before the front desk reads it to you.
Last reviewed: October 19, 2026